

Last Friday, I wrote that “the business week ended October 16, 2026, will either be remembered as the start of something or another false alarm.”
I was referring to a dastardly down-trade in chip stocks and rapidly deteriorating sentiment in the neocloud space, where CoreWeave struggled to convince a suddenly panicked market that reports of its demise were greatly exaggerated.
Although the jury’s still out on whether we did in fact witness “the start of something” mid-month, this week had the same ominous feel as its foreboding predecessor.
Big-cap US tech suffered its worst single-session loss in four months on October 22, CoreWeave was on track for a third straight weekly decline, South Korean stocks dropped another 3.5% following their worst week since the GFC and the “junkiest junk,” so to speak, blew out further.

CCC spreads are north of 1,000bps, with all-in yields around 16%. The figure above shows you the rolling one-month spread change for a universe of CCC and below credits.
Suffice to say the relative calm in higher-rated risk premia belies a pretty significant escalation in the lowest-tiered credits.
But really, you don’t have to go all the way down the credit ladder to see the stress. In fact, it’s readily apparent in spreads for the most creditworthy enterprises in the entire history of capitalism.
The figure below shows the cap-weighted spread on long-tenor hyper-scaler bonds.

As you can see, we’re around 130bps there, which is 40bps (give or take) wide to the broader IG universe.
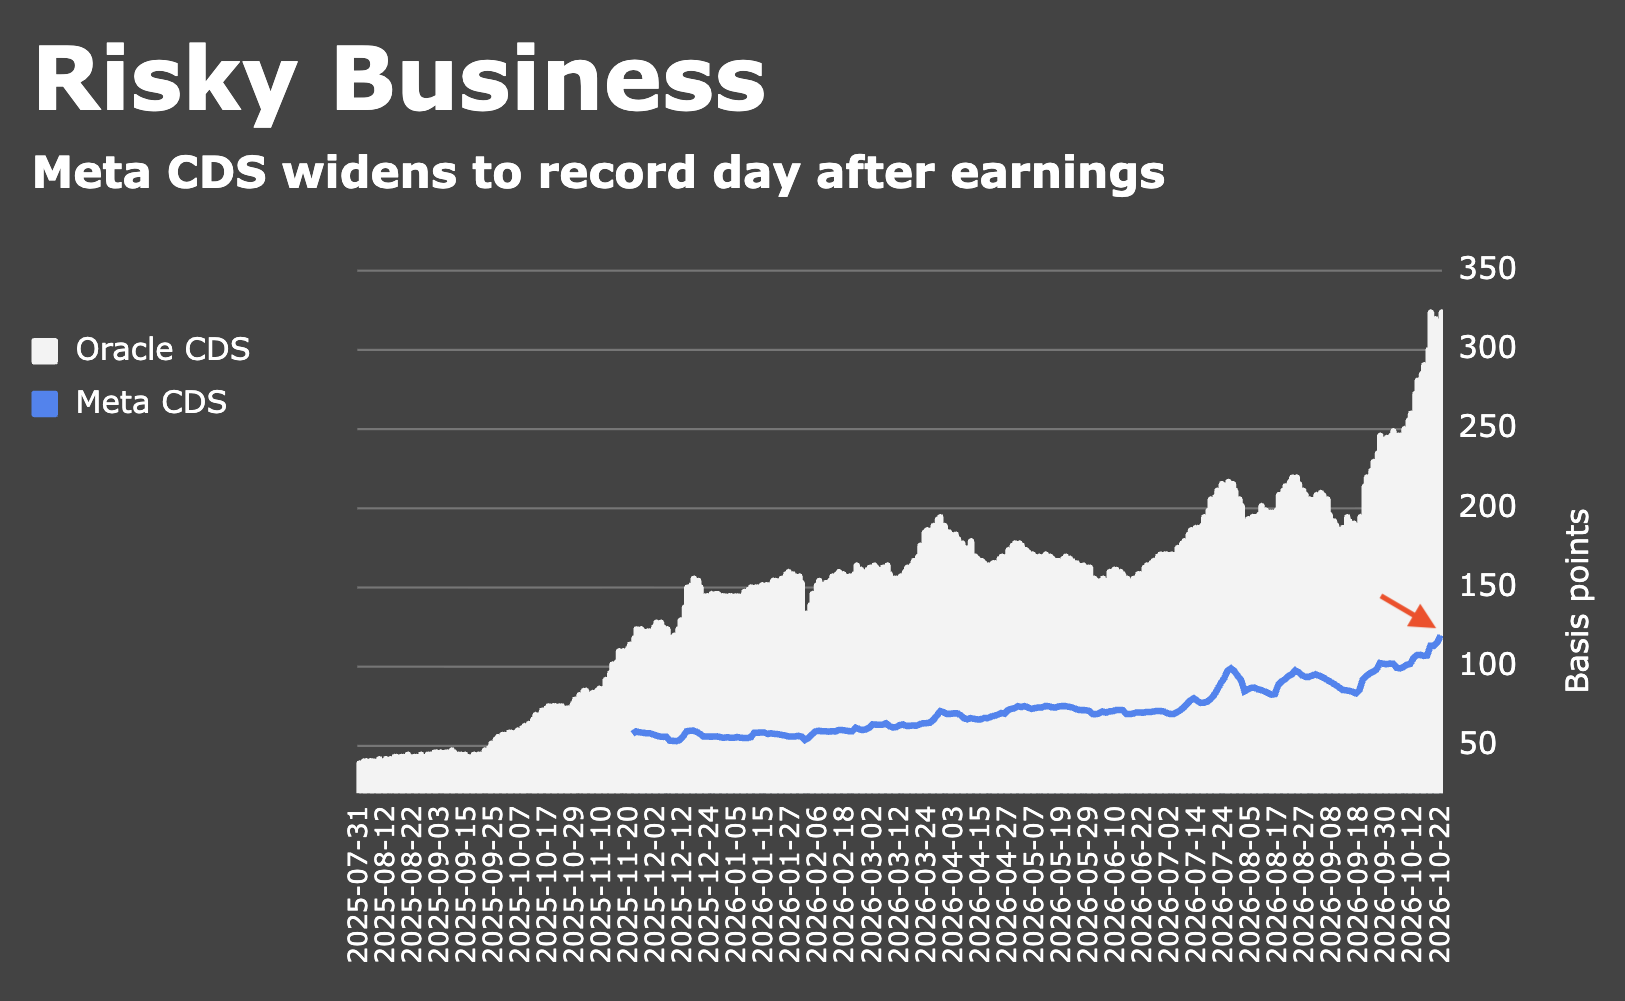
Whether that’s punitive enough to force “discipline” on the big-spenders I can’t say. Meta’s capex plans would suggest no, and Meta’s CDS would suggest the company’s becoming an incrementally riskier credit as a result.
But the important point is that a year on from the joining of the borrowing binge battle, we’ve reached some manner of inflection point beyond which the hyper-scalers, to say nothing of “subprime AI,” will be forced to contend with meaningful pushback on debt-funded data center outlays.

The figure above’s a reminder: The sheer scope of hyper-scaler “plus” SpaceX and Nvidia debt sales since Oracle kicked this whole thing off in September of 2025 is nothing short of staggering.
Nearly $390 billion in “additional” supply would be a lot of incremental paper for the market to underwrite over any temporal window. In the space of just 18 months (assuming the SpaceX deal comes to market at some point relatively soon), it’s a metric ton.
Remember: Other IG issuers, including the US Treasury, need to fund too. This data center debt is coming on top of “baseline,” if you will, high-grade supply.
The lead story on Bloomberg’s front page Friday warned that “AI fears” have driven global credit spreads to their widest since last summer, which is to say since the market was calming down after the “Liberation Day” shock.

There’s the chart on the relevant Bloomberg index. (Pro tip to the editors over there: If you put the legend on the left side, it squeezes the chart and makes it look more dramatic. Compress the y-axis and you’ve got yourself a bona fide piece of market doom porn.)
This — all of this — raises the already high stakes for imminent earnings reports from Alphabet, Amazon and Microsoft.
As I reminded readers on Thursday, the big-picture, medium-term question is whether the first evidence of capex restraint by the big spenders will be viewed as positive (i.e., a welcome sign of prudence and renewed discipline) or negative (i.e., a domino-tip moment).
We’re not likely to get any allusions to capex restraint from next week’s hyper-scaler reports. In fact, we’ll probably get the opposite. Here’s hoping the Google Cloud, AWS and Azure growth prints are robust enough to justify the profligacy.


I’m spending a lot more money on AWS every month