

Is the great American “profit boom” coming to an end?
Spoiler alert: Probably not, and even if it is, jumping to any sort of conclusions with just ~10% of S&P 500 earnings on the books is something worse than a fool’s errand.
Still, I suppose it’s worth noting that one week in, Q3 reporting season’s not exactly gangbusters. As you might’ve seen sandwiched on Bloomberg’s front page between dire-sounding political headlines out of Europe, Wells Fargo’s out declaring this “one of the weakest starts to EPS season in history.”
I tracked down the relevant note and… well, suffice to say I’m not personally prepared to jump off any bridges, but to each his own. Rather than criticize anyone’s analysis, I’ll just give you the actual numbers: Of the 45 S&P 500 companies that had reported by the end of last week, 82% of them beat consensus in absolute terms (i.e., whether by a penny or by a dollar) and 53% by at least one standard deviation of analyst estimates.
That latter metric is what Goldman prefers, and as the figure on the left below shows, 53% does in fact count as a deceleration, even as it remains slightly above the long-term average.

The figure on the right shows you a prospective “roll over” moment for revisions breadth, although there again, “moderation” is the better word for now.
Even if earnings growth does slow, stocks should be ok. “Equities should continue to rise as long as earnings continue to grow,” Goldman’s Ben Snider remarked, adding that “positive but decelerating growth has historically been associated with positive but moderating returns.”
I know what you’re thinking: Gosh, if Snider’s under 40, give him a Fields. But before you despair that folks like Ben make many multiples of a first responder’s salary to surmise that the value of stakes in publicly-traded companies tends to ebb and flow with the profits of those same companies, note that context is key: The reason equities have held up in the face of myriad headwinds including five-handle 10-year Treasury yields, near-3% real yields, triple-digit crude and the onset of a Fed hiking cycle (however shallow it ends up being) is that earnings grew faster in Q1 and Q2 than almost any other quarter in living memory excluding recession rebounds. That’s true even when you exclude write-ups at Amazon and Alphabet.
When set against an index that mostly moved sideways in recent months, that historic profit boom and expectations of more to come translated into a meaningful de-rating which saw the S&P trade 3-4 turns cheaper headed into Q3 results.
So, questions about the sustainability of robust earnings growth burn far (far) hotter than they would normally. Absent that growth impulse, equities may not prove as impervious to an unforgiving macro environment, and in the event profit expectations recede, the index’s forward multiple would mechanically re-rate (i.e., the index would become more expensive assuming it doesn’t sell off first).
With that in mind, Goldman still expects aggregate index EPS of $415 in 2027 from $375 this year.
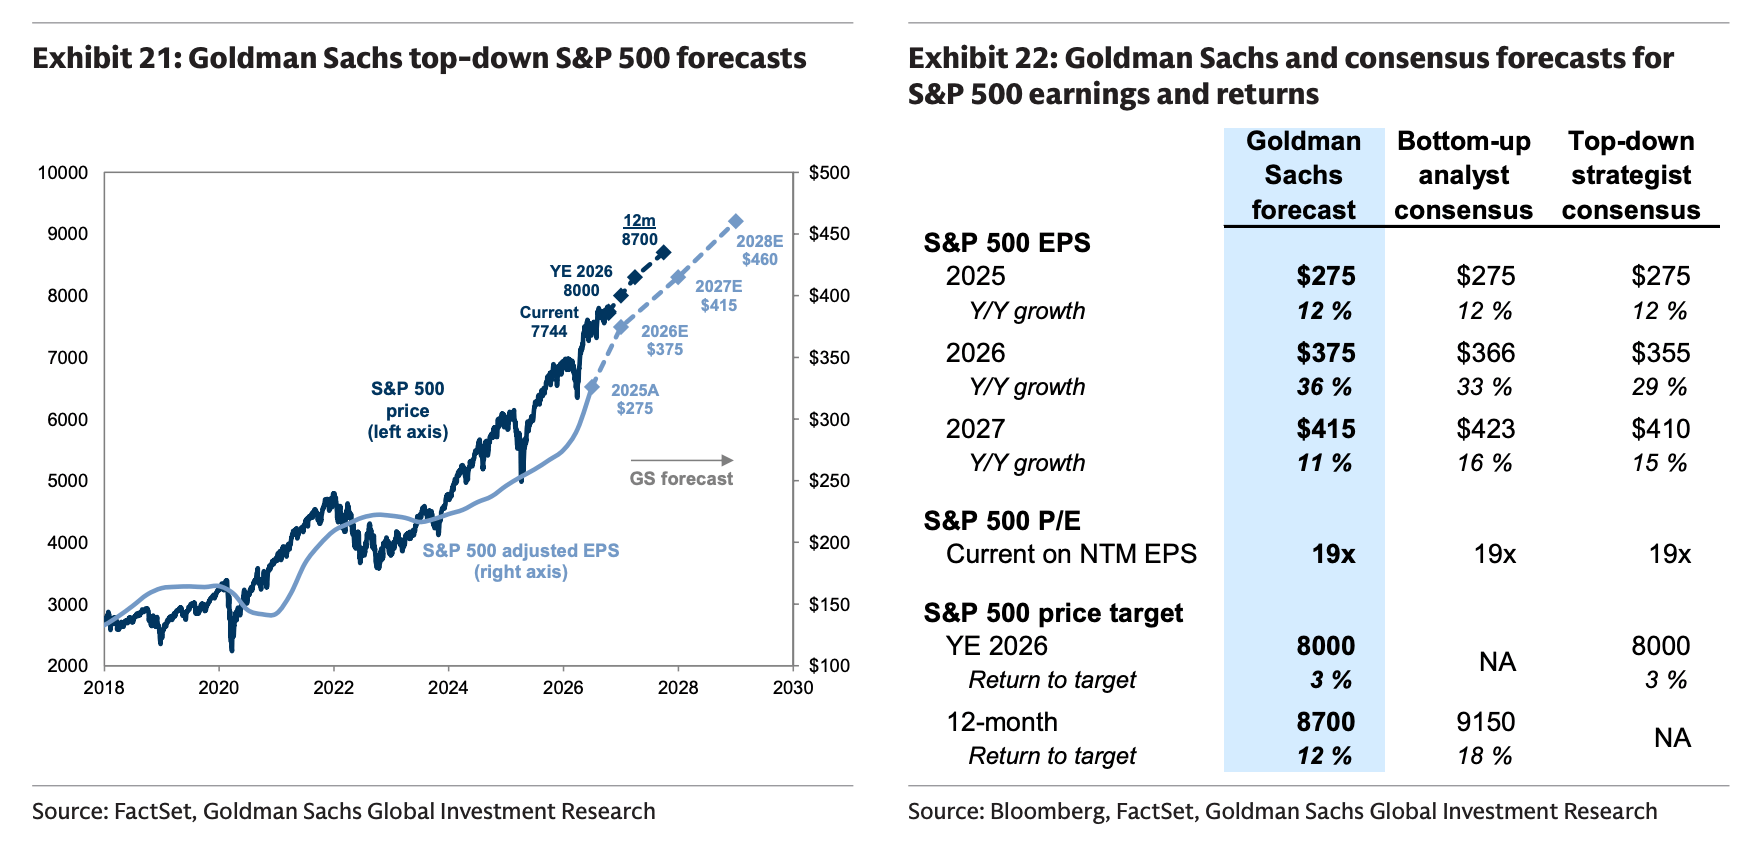
The figures above give you an updated snapshot of the bank’s forecasts as well as a look at how Snider’s outlook compares to his peers around the Street and also to bottom-up consensus.
On the surface, $415 for aggregate index EPS in 2027 would mark a dramatic deceleration in bottom-line growth given that $375 for 2026 represents better than 35% growth versus 2025. But when you strip away the above-mentioned “other income” (i.e., the 2026 earnings boost from mega-tech’s stakes in private companies, namely Anthropic), the projected growth rate for 2027 goes from less than 11% to something like 18%, and that includes an adjustment to account for what Snider described as “a modest deceleration in real US economic growth” in the coming quarters, as higher oil prices and rates bite.
Take all of that for what it’s worth. If you’re inclined to say it isn’t worth much, and certainly not ~6x a first responder’s salary, I won’t argue. But hey, somebody’s gotta buy the Hermès ties. And it ain’t gonna be me. The valets wouldn’t love me anymore if I wore real suits instead of track suits.


