

“Harry, I know you’re pissed. We had a setback.”
“Listen, Scott, I am in a heap of trouble here. I was supposed to buy a house for my family and now we’re gonna lose the house.”
Have you seen Boiler Room? If not, watch it tonight. You’ll love it. And then you’ll get the joke.
I retell this story all the time, so I’ll make it short. A week or so after Donald Trump’s second inaugural, Scott Bessent showed up on Fox to chat with Larry Kudlow. He (Scott, not Larry) said Trump was laser-focused on 10-year Treasury yields because getting those yields lower would provide relief for American families in the form of, for example, cheaper financing for otherwise unaffordable houses.
Fast forward 20 months and we can definitively call that an unkept promise. On Wednesday, the MBA said mortgage rates rose nearly 20bps over the last week as the US long-end continued to trade wild and heavy, pushing 10-year yields to their highest levels since 2002.
The latest increase, which drove the average 30-year fixed near 7.50%, came atop an 18bps jump the prior week, a 15bps ascent the week before that, a 12bps climb the week before that and… well, I’m running out of synonymous for “increased.”

As the figure shows, the seven-week increase is now nearly three-quarters of a percentage point. Rates are almost 150bps higher since the war started.
I’m not being hyperbolic to call that an epic disaster. There’s no telling how many home-buying plans were derailed by this over the past two months. Simply put: If you didn’t lock then shop, you were (and remain) screwed.
It’s not just the rise in yields, it’s the accompanying rate vol. In addition to the read-across from the highest 10-year yields in decades, “spreads widened with the increase in volatility,” MBA VP Joel Kan said Wednesday. “Purchase activity decreased across all loan types,” he added.
This is only getting worse. Note that rates actually hit 7.61% on Monday, according to Mortgage News Daily’s more timely tracker. Tellingly, Tuesday’s marginal decrease counted as just the seventh daily decline since August 25, and that was set to reverse on Wednesday as bond yields climbed anew.

The figure above shows you the rolling two-month change on the MBA’s gauge. Again: This is a disaster, both economically and politically ahead of the midterms. (I hope you get that $5,000 from him, because you’re gonna need it.)
According to Redfin, more than one in five sellers cut their asking price in the four weeks to September 20, which Dana Anderson noted was “the highest share for this time of year in our records.”
Still, she said, price drops are “only slightly more common” despite the strongest buyer’s market ever. “Many would-be sellers are waiting to put their home on the market and others are delisting if they don’t get their asking price,” she wrote.
In the same piece, Anderson quoted Redfin’s Senior Economist Asad Khan. Sellers who actually want to get deals done “need to come to terms with reality,” Khan said. “Mortgage rates are sitting above 7%, the economy is uncertain and many homes are lingering on the market.”


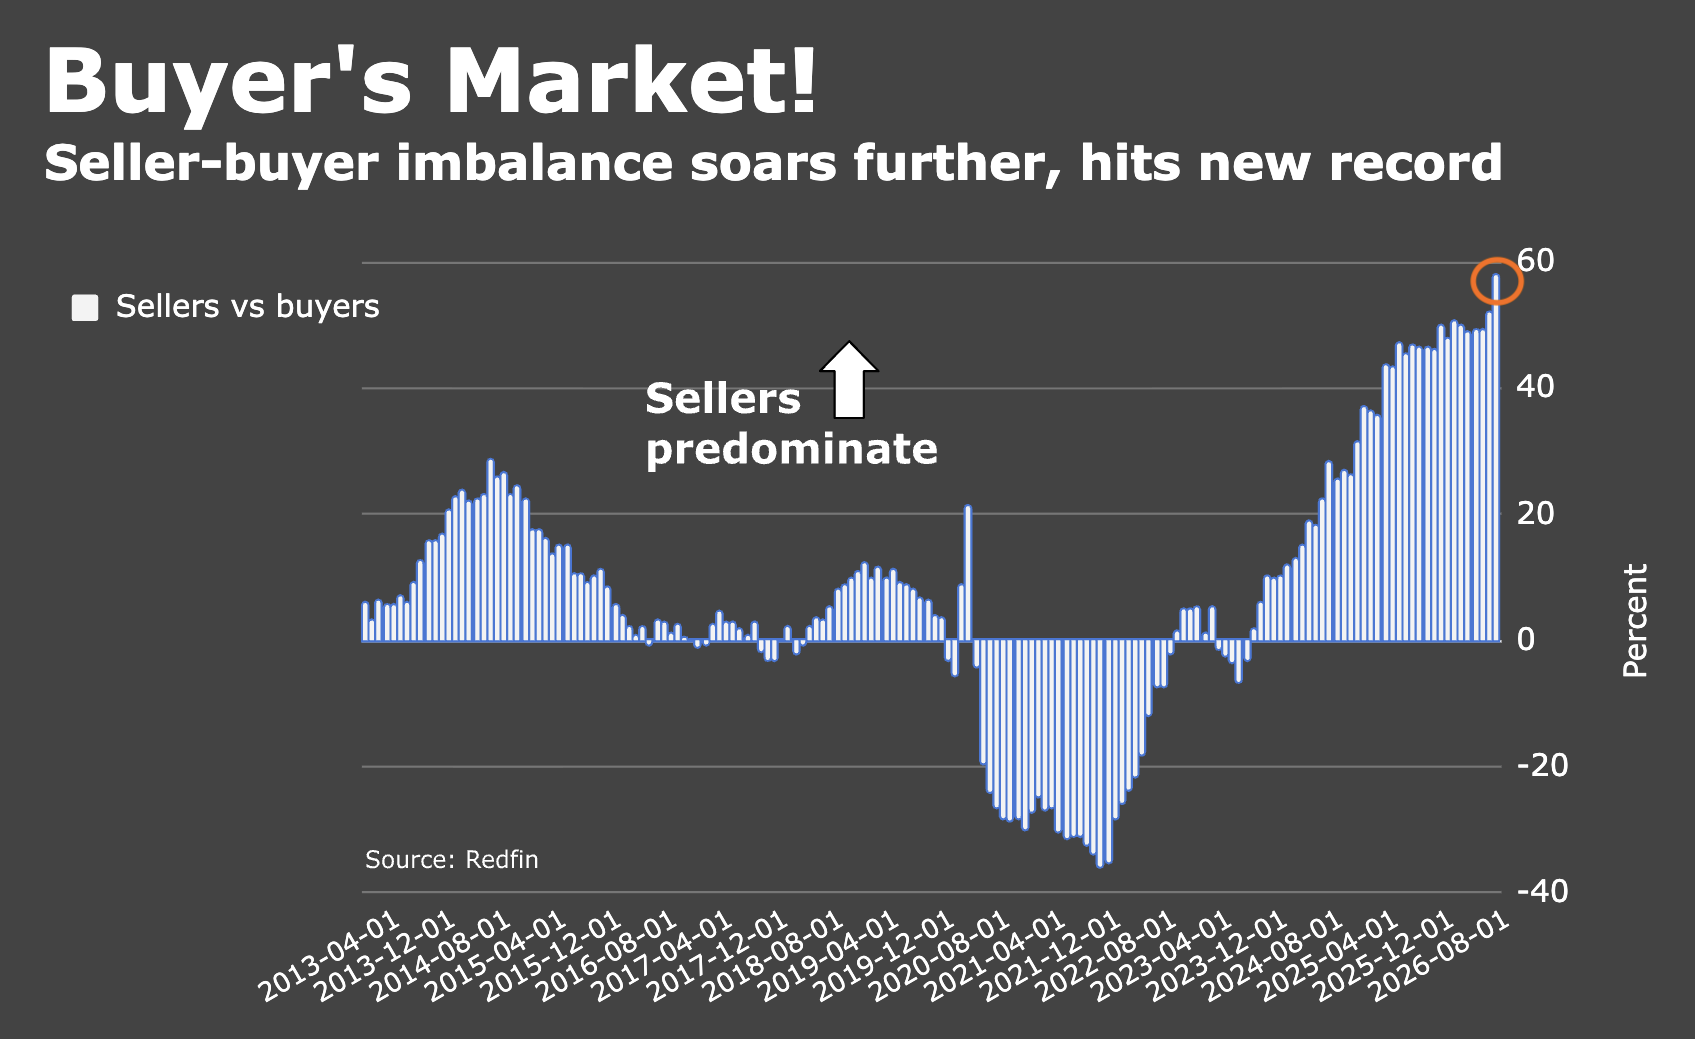
This won’t/doesn’t sit well with a populace that’s been conditioned from birth that the American dream includes a home of their own. Trump’s economic miracle is just another casino gone bust. But, as is typical, he’s walking out the door with a couple of billion stuffed in his pockets. Want to turn off voters? Don’t deliver what you promised, but make sure you and yours are well compensated. That’s a double gut punch.
Populism a la Trump was a con for the benefit of the wealthy and corporates, and its failure will beget more populism, and more again, with an uncertain destination.
Up to 10% of home mortgage last year were variable rate.
Imagine already owning a home, purchased with an ARM three to five years ago, and you relied on the mortgage banker saying, “Well of course rates will be lower when the adjustment arrives.” I have two friends in this spot. They bought in the back half of 2022 just as mortgage rates were spiking. They, somewhat reasonably at the time, thought that it was an aberration. Or, those families who bought a house post-Covid, stretched because of the market at the time, still caught the last of the low rates but had to use an AMR because of their personal financial situation. Those poor folks are especially screwed because they already own the house and about to get adjusted significantly upward. Sucks.
7.61%. Lower than any rate I had for any house my wife and I owned from 1970 through 1992.
Which, with apologies, isn’t any more comforting for younger Millennials trying to buy their first home than reminding someone who can’t afford an iPhone that even the cheapest flip phone is a far superior piece of technology versus a rotary. I mean, we’re talking about people who weren’t even born until 1992. They’re not thinking, “Well, it could be worse!” Paul Volcker may as well be Charles Sumner Hamlin to these adult children.
In 2024, the average priced home cost around $400,000. That is 5x median household income. In 1980, the average priced home cost ~2.5x median household income.
Respectfully, while you may have had a higher rate, your entry price was significantly less.
Meanwhile “the House” fires off his bitty little bond buybacks as “the Market” LMAOs.
I read a blurb yesterday that bank foreclosures on homes this past August were up 42% YOY. Recall, the Trump administration moved to curtail loan modifications and extensions on government-backed loans some time ago. I believe October was (is) the final deadline for those.